Originally published at: Inflation Is Running Hot and AI Is Beginning to Crack – Peak Prosperity
In this week’s podcast with Paul Kiker, we discussed the hot CPI reading indicating that cost-push inflation has arrived. We both think it’s going to get worse before it gets better.
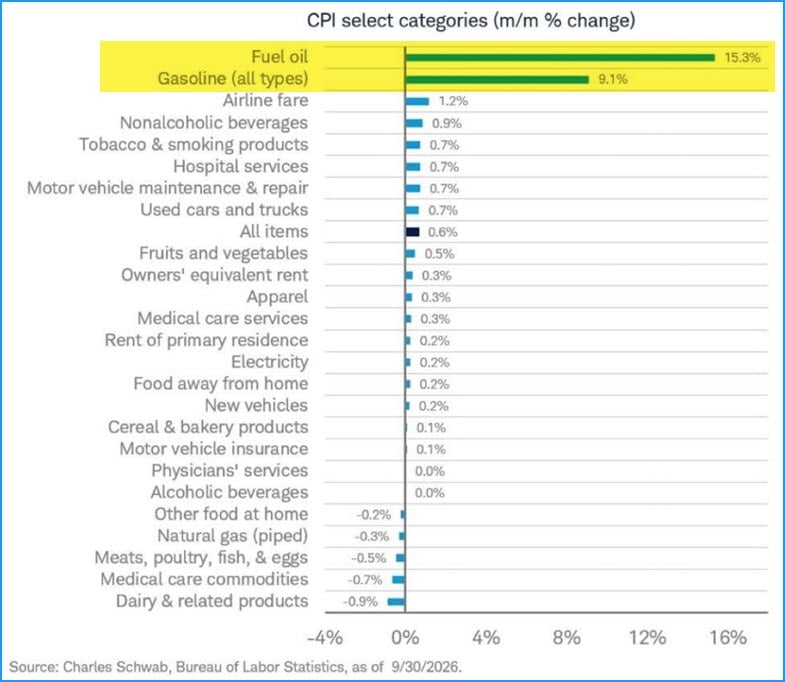
Couple that with today’s super-hot PPI (Producer Price Index) reading, and it helps to explain why so many S&P 500 member companies are seeing their stocks ‘sneak off the field,’ leaving only the AI generals to hold everything up.
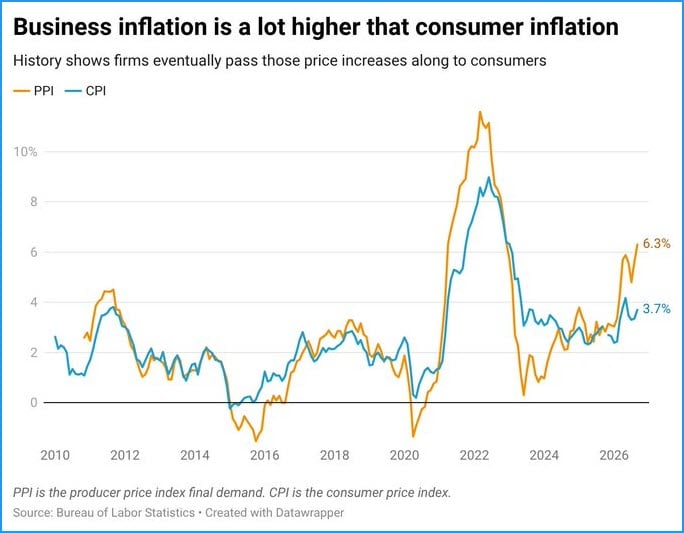
Explanation: A high PPI reading but a lower CPI reading means companies are eating the difference by choosing not to raise prices, which means lower profits are the result.
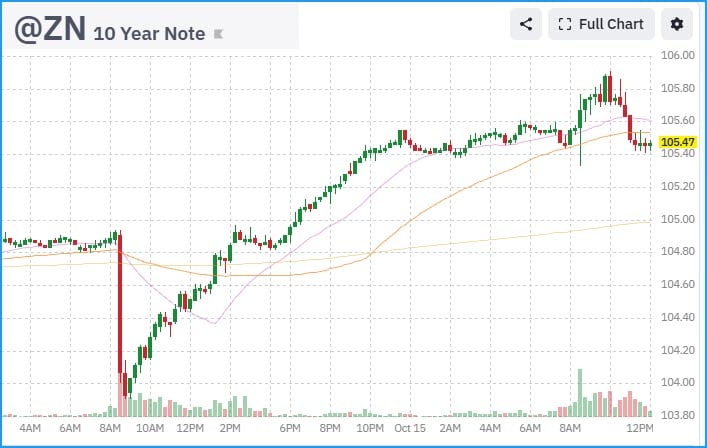
We also observed ed super-unusual behavior in the 10-year Treasury market where the bond immediately sold off in reaction to a rising CPI (as it should; bonds hate inflation), but then rather dramatically “went the other direction” as if grabbed by the collar and frog-marched to a higher price and lower yield.
This smacks of manipulation, but perhaps that should be a surprise given how overt insider trading is even being openly swept under the rug:
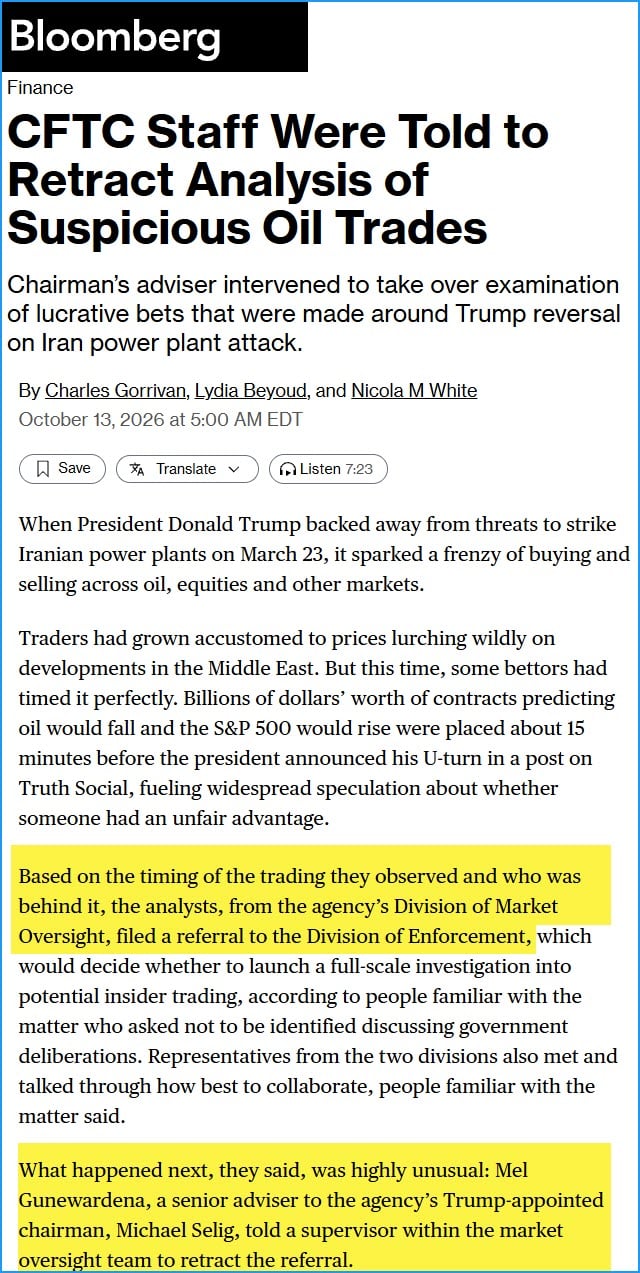
How crazy is that?
I get the sense that “someone” is doing everything possible to force the ““markets”” to behave before the midterm elections. But can they hold it all together? This is a serious concern for everybody with wealth in these bizarre times.
All I know for sure is that eventually gravity will win, and that your best chance of making it through the eventual corrections will be to have a solid strategy in place and to manage risks as well and as prudently as possible.
Note:
I find AI summaries to be quite useful. So here’s an AI summary of this week’s podcast. I’ll probably start including these going forward, but rest assured I will always be crystal clear when something is written by AI. Otherwise, I write everything that carries my name.
AI Summary
- Official inflation is understating the cost-of-survival rise, and the Fed cannot touch the driver. September CPI printed 3.7 percent on surging gas and fuel oil (diesel up 15.3 percent month-over-month, gasoline 9.1 percent). Martenson mentally adds two points; BLS claims that medical premiums fell 31 percent over five years while clients report the opposite on utilities, meat, and restaurants. These are cost-push pressures from the Iran and Russia wars. Rate hikes or cuts do nothing to refinery damage or shipping losses, so the Fed is watching a number it cannot change.
- Markets are being managed, and the last fig leaf of enforcement just came off. The 10-year bond V-bottomed on huge volume the instant the inflation print hit, behavior Martenson had seen in stocks but not before in Treasuries. Oil refuses to price the physical damage. A Bloomberg report states that CFTC market-oversight staff filed a referral on large short bets placed minutes before Trump’s reversal on Iran power-plant attacks, and a senior advisor to the Trump-appointed chairman ordered the referral retracted. Kiker calls it open insider trading with rules for thee but not for me, and compares the feel to the late-stage fraud he and Martenson watched in 2006–07.
- The AI growth story is hitting a physical wall while everything else is already concentrated and cracking. Five stocks are carrying the S&P. CoreWeave debt CDS has blown out past 1,000 basis points. The grid interconnection queue is twice the size of the existing grid; PJM is already in emergency. Prompt Brent is ~$126 versus the futures screen near $106; landed barrels run $150–160 once freight is added, and New York Harbor diesel crack spreads jumped $12 in a single day. Exxon is breaking out. Commercial towers are selling for pennies or drawing zero bids. The combination is a debt, technology, and housing bubble at once, with no remaining savior asset class.
Chris and Paul open on the September CPI and the gap between the headline and what people actually pay for fuel, food, and shelter. They treat the energy component as interest-rate insensitive and therefore outside the Fed’s reach, while the rest of the tape is being held together by intervention: bond V-bottoms, oil containment into the election, and a CFTC referral that was ordered withdrawn. Under the surface, the AI infrastructure spend that has propped earnings is colliding with diesel, sulfur, and grid limits that cannot be printed away. Commercial real estate is already clearing at distressed prices, mortgage rates near 8 percent are freezing household transactions, and the younger cohort faces rising rates with no refinancing escape hatch. Their practical close is the same as prior episodes: the rules can still be gamed for a while, but an exterior force (bond vigilantes, a diesel shortage, or the five stocks rolling over) will eventually enforce fiscal reality, so sweep profits, hold multi-year cash, and decide in advance what would make you sell.
Timestamps
00:00 Inflation’s Second Act Is Coming
01:09 The Numbers Don’t Match Reality
04:27 Inflation Becomes A Survival Problem
06:38 Bond Yields Are Acting Strange
08:00 Washington’s Debt-Dodging Strategy
11:00 The Bond Vigilantes Are Warming Up
13:37 Did Someone Rig The Oil Market?
16:55 Insider Trading, Officially Unwelcome
21:00 Rules For Thee, Not For Me
25:01 Five Stocks Hold Up The Market
26:08 The Market’s Hidden Carnage
31:29 AI’s Growth Story Hits A Power Wall
35:38 Energy Infrastructure Under Attack
39:34 Oil’s Price Suppression Problem
42:36 The Inflation Echo Of The 1970s
45:31 The End Of Easy Money
48:15 Commercial Real Estate’s Fire Sale
52:03 Three Bubbles And A Crisis Of Judgment
54:08 Preparing Before The Market Breaks
FINANCIAL DISCLAIMER:
The information contained in this video and the resources available for download through our affiliated website are not intended as and shall not be understood or construed as financial advice, nor should be interpreted as a solicitation to sell or offer to sell investment advisory services. No person who currently works for or contracts with Peak Prosperity or Peak Financial Investing is an attorney or accountant, nor are we holding ourselves out to be, and the information contained in the video and on the website is not a substitute for legal or tax advice from a professional who is aware of the facts and circumstances of your individual situation. While Peak Financial Investing is a registered investment advisor, please note that this podcast is not intended to be investment advice.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information, and it should not be relied on as such. We have done our best to ensure that the information provided is accurate and provides what we feel is valuable information. The views expressed are subject to change based on market and other conditions.<
No guests or clients appearing on the podcast receive any form of compensation for their appearance and obtain no other benefit from either Peak Prosperity or Peak Financial Investing.
All investing involves risks including the possible loss of capital. Asset allocation and diversification do not ensure a profit or protect against loss. Please note that outperformance does not necessarily represent positive total returns for a period. There is no assurance that any investment strategy will be successful. All investments carry a certain degree of risk. Dividends are not guaranteed, and a company’s future ability to pay dividends may be limited.
Additional important disclosures for Peak Financial Investing may be found in our Form ADV Part 2A, which can be found at https://adviserinfo.sec.gov/firm/summary/319672.