Understanding the Stark Difference Between Passive Investing and an Active Risk-Managed Strategy

Originally published at: Understanding the Stark Difference Between Passive Investing and an Active Risk-Managed Strategy – Peak Prosperity

Last week, Paul Kiker took us through the retirement and financial planning process he uses with every prospective and existing client. That generated a lot of interest and led to several questions we’re going to address.

So today is about understanding the pros and cons of both passive investing and taking an active, risk-managed approach.

As with all complicated things, there’s no one right answer because investors come in all sizes, ages, and unique financial circumstances.

Passive investing essentially means staying invested according to a predetermined allocation, regardless of changing market conditions, valuations, or emerging risks.

For example, doing a monthly 401(k) contribution (perhaps with a company match) that goes into a 60/40 set of stock/bond funds. Is the market up? The money goes in. Is the market down? The money goes in. IS the market fairly priced? The money goes in. IS the market wildly overpriced? The money goes in.

Paul makes the case that passive strategies can make sense during the accumulation phase of life, when younger investors not only have decades to recover from market declines but benefit from buying at lower prices.

But a retiree (or someone close to retirement) can be absolutely devastated by a downturn coming at the wrong time for their life’s financial arc.

Alternatively, a risk-managed strategy continually assesses upside potential versus downside risk, establishing decision points at which investments are reduced or exited when the risk-reward relationship deteriorates, and which are increased when the risk-reward relationship is favorable.

The way Paul executes a risk-managed strategy removes emotions from the decisions and follows a plan with clear advantages and disadvantages that fit within a defined plan that has clear goals.

We also spent some time distinguishing volatility from risk. This is important because Wall Street and its marketing arms (CNBC et al.) have spent decades trying to get everybody to conflate the two.

So, here goes. Volatility describes the movement of asset prices in either direction, while risk exists in situations where the potential downside becomes disproportionately large relative to potential upside.

You know what’s made this all much harder to navigate? Constant government and Fed interventions. Those have inverted, if not perverted, the usual market signals that provide insights into actual market risk and reward.

But, as Paul says, you have to play by the rules as they are, not as we wish them to be.


Timestamps

00:00 The Risk of an Overvalued Market
00:38 Why Passive vs. Active Matters
02:57 What Passive Investing Really Means
05:13 When Passive Investing Buys Regardless
09:43 Why Time Changes Everything
13:49 How Passive Investing Can Hurt Retirees
16:00 What Risk Managed Investing Does
23:19 Volatility Is Not the Same as Risk
28:40 Measuring the Downside Risk
36:50 The Pros And Cons of Passive vs. Active
40:47 What History Says About Retirement Risk
42:44 Why Investors Are Getting Twitchy


FINANCIAL DISCLAIMER:

The information contained in this video and the resources available for download through our affiliated website are not intended as and shall not be understood or construed as financial advice, nor should be interpreted as a solicitation to sell or offer to sell investment advisory services. No person who currently works for or contracts with Peak Prosperity or Peak Financial Investing is an attorney or accountant, nor are we holding ourselves out to be, and the information contained in the video and on the website is not a substitute for legal or tax advice from a professional who is aware of the facts and circumstances of your individual situation. While Peak Financial Investing is a registered investment advisor, please note that this podcast is not intended to be investment advice.

All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such. We have done our best to ensure that the information provided is accurate and provides what we feel is valuable information. The views expressed are subject to change based on market and other conditions.<

No guests or clients appearing on the podcast receive any form of compensation for their appearance and obtained no other benefit from either Peak Prosperity or Peak Financial Investing.

All investing involves risks including the possible loss of capital. Asset allocation and diversification does not ensure a profit or protect against loss. Please note that out- performance does not necessarily represent positive total returns for a period. There is no assurance that any investment strategy will be successful. All investments carry a certain degree of risk. Dividends are not guaranteed, and a company’s future ability to pay dividends may be limited.

Additional important disclosures for Peak Financial Investing may be found in our Form ADV Part 2A, which can be found at https://adviserinfo.sec.gov/firm/summary/319672.
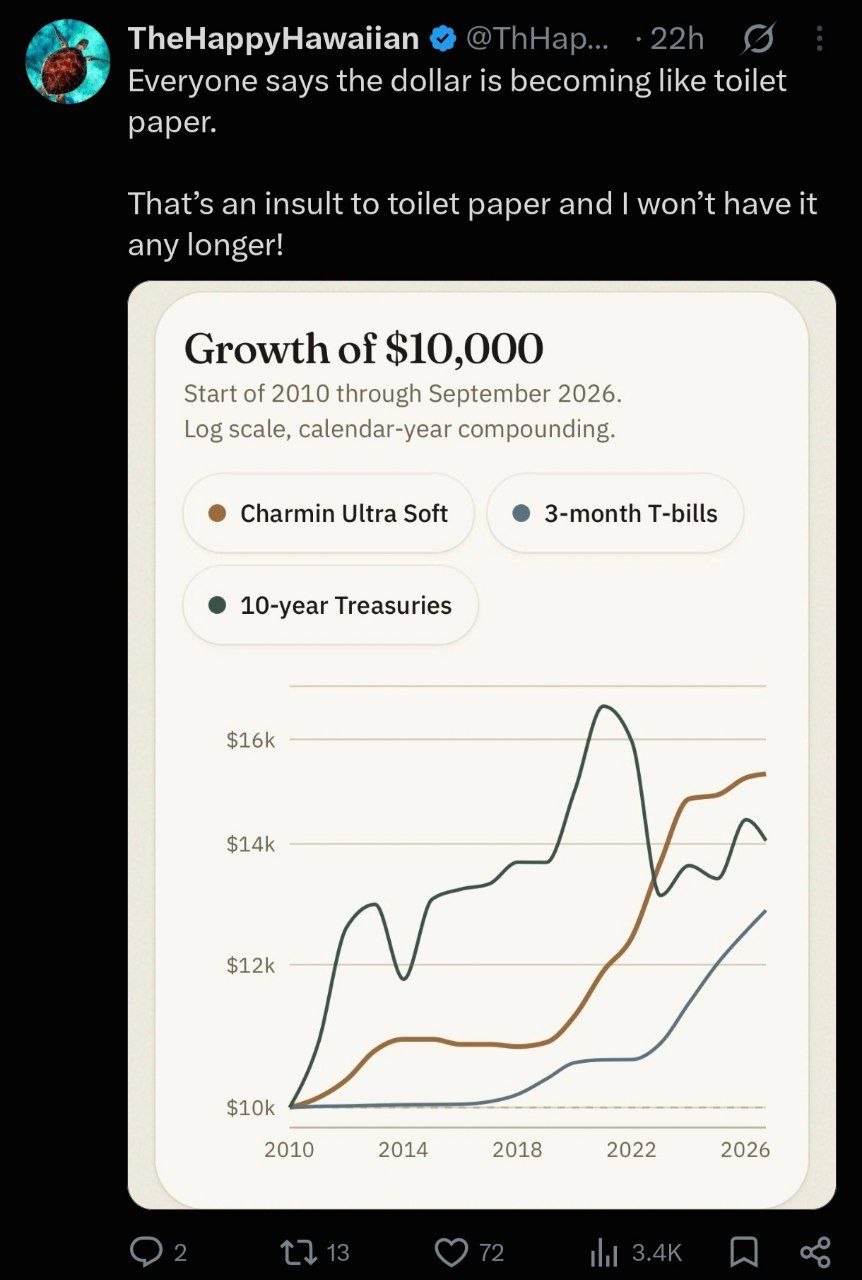
Asides from certain stocks and PMs I’m getting better performance from buying freeze dried food, and ammo subscriptions than bonds. Hell, even toilet paper is giving them a run for their money.

8 Likes

6 Likes

There was a time in the history of financial theory when risk was defined as the probability of getting a return other than expected. Statistically, risk was the standard deviation of a distribution of possible returns, where the mean was the expected return. That is, risk was essentially measurable if one had enough reliable data. Uncertainty was something else; essentially outcomes that were unknown, or unable to be measured.
A focus on ‘downside’ outcomes relative to ‘upside’ outcomes fails without probabilities–it becomes a guessing game, more so when uncertainty enters the picture.
A passive buy-and-hold strategy essentially reflects the long-term trend, which includes both real long-term growth and inflation components. The return is an average over a longer period of time, with generally lower risk. Note that the post-2008 buy-hold return is relatively high–that’s inflation from sub-zero real interest rates
An active strategy of buying low and selling high essentially incorporates the business cycle growth phase, and avoids the decline phase, significantly increasing returns relative to risk. Sheltering capital during downturns maintains wealth. Add in systematic strategies and returns are even higher. Astute investors used to buy bonds, gold, utilities, and public storage companies in downturns.
Which brings us to 2026. We have not experienced anything like this. Enormous debt loads globally, overpriced markets, low savings rates, a decade+ of sub-zero real interest rates, risk-return relationships trashed, excessive speculation, massive manipulation, Fed dependence… it’s a long list.

IMHO, it’s time for the Stoic approach: Premeditatio Malorum…Prepare for the worst. That’s not passive, or active, or systematic. It’s man the lifeboats, because if the situation deteriorates enough, uncertainty implodes the system, and all bets are off.

1 Like

I just restained my decks, using 4 gallons from a stockpile, and 2 additional gallons that cost more than the original 4 did. Unintentionally, a better return on investment over few years than most things. To paraphrase Mark Twain, ‘predicting the way things work out is particularly difficult when dealing with future’. I keep coming back to: one third for inflation, one third for deflation, and one third for disaster. Two out of three, is not looking good, to look forward to.

2 Likes

I really liked your exposition on risk vs expected returns vs uncertainty.

Let me add the REALLY BIG THING that I believe is going to confound historical comparisons and every solidly back-tested model.

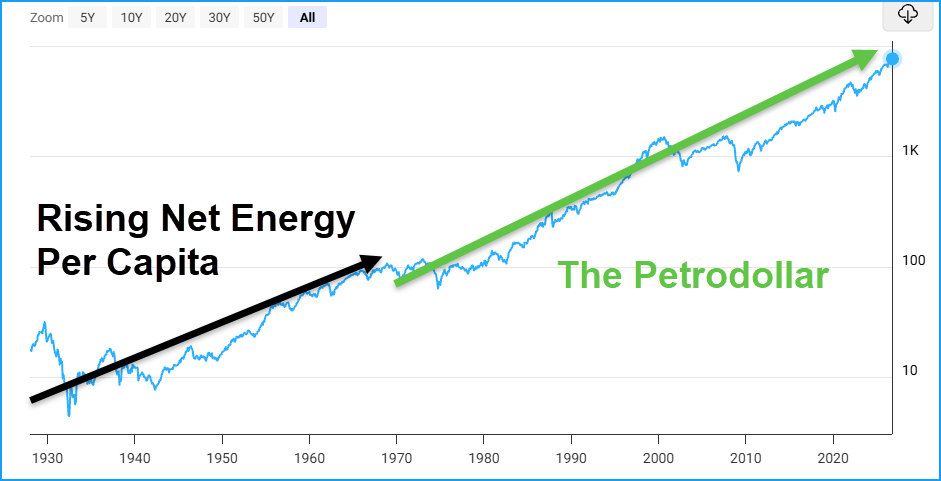
Let’s divide the US into two periods. In the first period (in black, below) our own energy abundance delivered both the opportunity and the reality of rising general prosperity. This is the era that the MAGA people rightly and nostalgically wish to return to:

But then conventional oil peaked in 1970 and, no matter the propaganda, has never reclaimed that former glory. Shale oil got there volumetrically later on, but never on a per capita surplus energy basis.

The artful dodge of this unfortunate geological reality was Kissinger’s brilliant idea to convert to the petrodollar (The green arrow above). This allowed the US to convert other countries’ surplus energy into our own elevated living standards.

Genius! Evil, but genius.

Okay…where am I going with this?

Back to the S&P chart.

A prime reason that the powers that be got away with inflating everything over all of those decades and centuries (19th and 20th) is because the energy was there to make it all seem quite reasonable.

But is it reasonable to keep extending a log chart of the S&P 500 into the future, here and now?

Yes, of course, but only if there’s the same underlying net energy per capita to make it all pencil out.

And this brings us to the elephant in the room, the REALLY BIG THING.

Now I cannot make the case that the US will be the preferred destination for the remaining allotments of high net energy oil. I can make stronger cases for other locations being the recipients. China being one, but also many other deserving nations who do not resort to bully diplomacy.

Which means that the primary underlying value driver of the S&P 500 is no longer a slam-dunk certainty to wind up powering the US economy.

The roving eye of beneficence lands where it will. In the Renaissance period, it landed in Venice, Italy. Later in Paris. For a while in England.

It flits about. Nobody has figured out how to get it to land in a particular spot.

But I do know this…when your energy leaves you, you are no longer a candidate spot.

2 Likes

“… The roving eye of beneficence lands where it will…” I expect where it lands it is not random. Rather, there are unique factors that bias beneficence, not unlike those inherent attributes that determine the success/location of cities/towns. The west coast of Africa, for example, precludes major ports, while the east coast of North America provides an abundance of ports.

While the demand for energy will likely continue to increase, the form of that energy is already changing, slowly supplanting the oil-based economy. AI is the first salvo in the current economic evolution, with robotics close behind. Does the petrodollar have a role in that, when the US abuses its leadership privilege–your bully diplomacy? Local nuclear plants and fuel cells will change the energy economies of scale, and eventually, superconductor power grids…

Back at the roving eye of beneficence, the most valuable factor of production is innovation, since it sees beyond what currently exists. Innovation got the US to where it is today, but education sucks, and critical and creative thinking are in very short supply. Worse, AI does little to actually develop either one.

The prognosis is not good.